Real Estate Information Archive

Blog

Displaying blog entries 1-2 of 2

Home Prices Are Becoming More Negotiable

You find a home you love, check the price, calculate the monthly payment—and close the app.

If that sounds familiar, there’s good news: buyers may have more negotiating power in today’s housing market.

More homes are sitting on the market, while fewer buyers are competing for them. That’s pushing sellers to lower prices and make their homes more affordable.

4 Out of 10 Sellers Are Cutting Prices

According to Housing Wire Data, more than 40% of sellers are reducing their asking price.
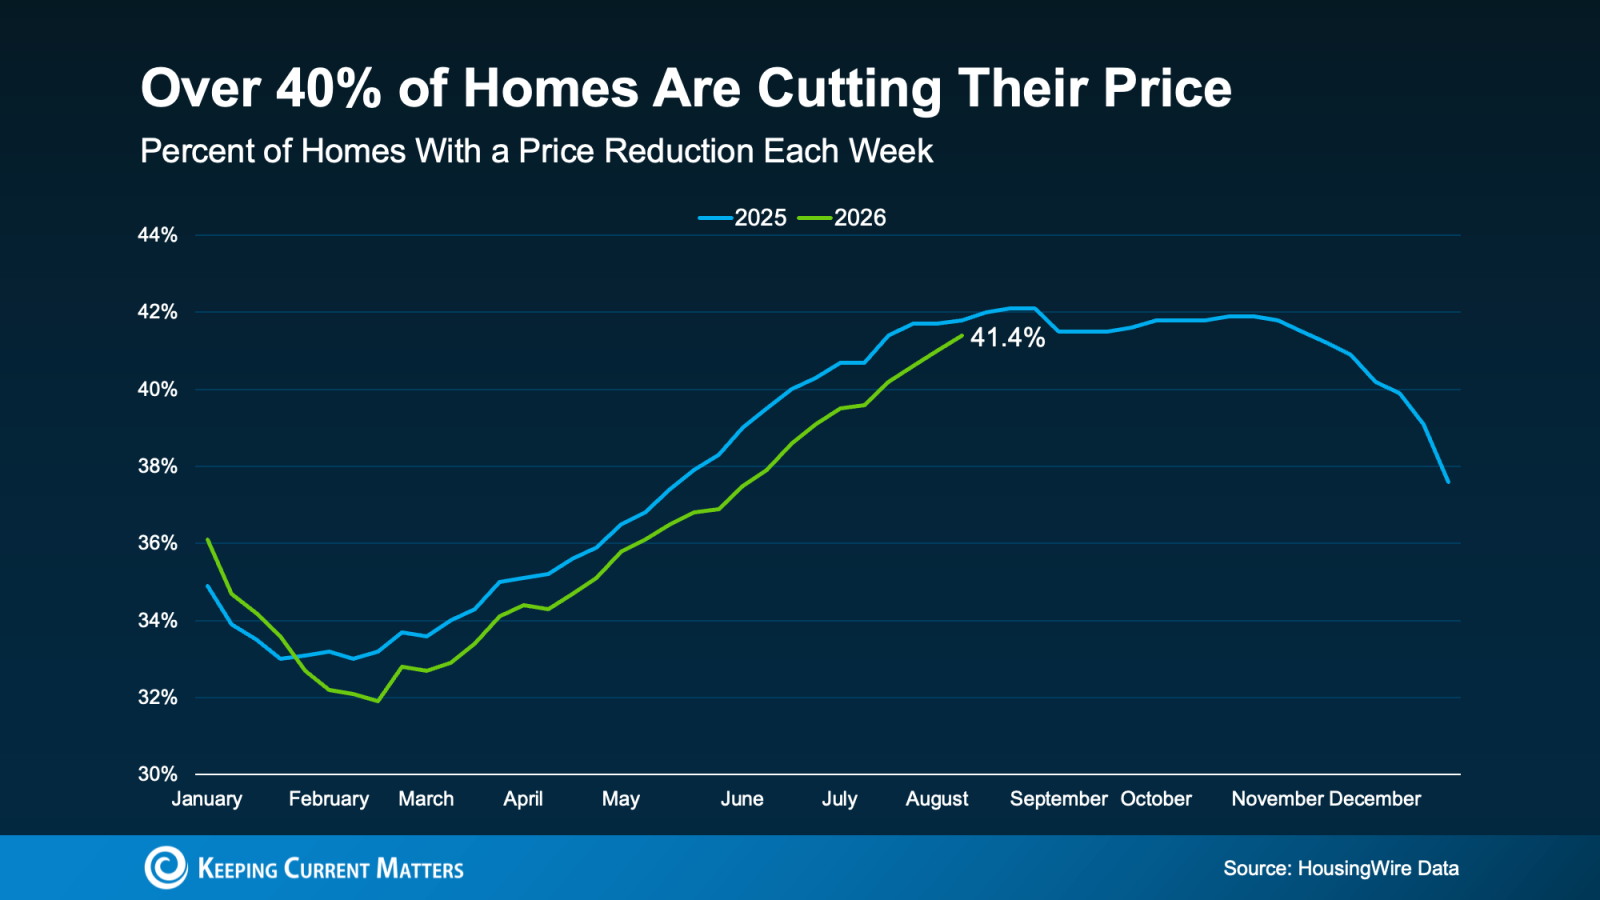
That means more than 4 out of every 10 homes are seeing price cuts.

Why? Sellers know buyers have more choices. If a home isn’t attracting offers, lowering the price can be the best way to get buyers’ attention.

As Danielle Hale, Chief Economist at Realtor.com, puts it:

“Sellers are meeting the market with more realistic asking prices.”

Home Prices Are Becoming More Realistic

Price cuts aren’t the only change.

According to Realtor.com, July 2026 had the lowest median list price for any July in five years.
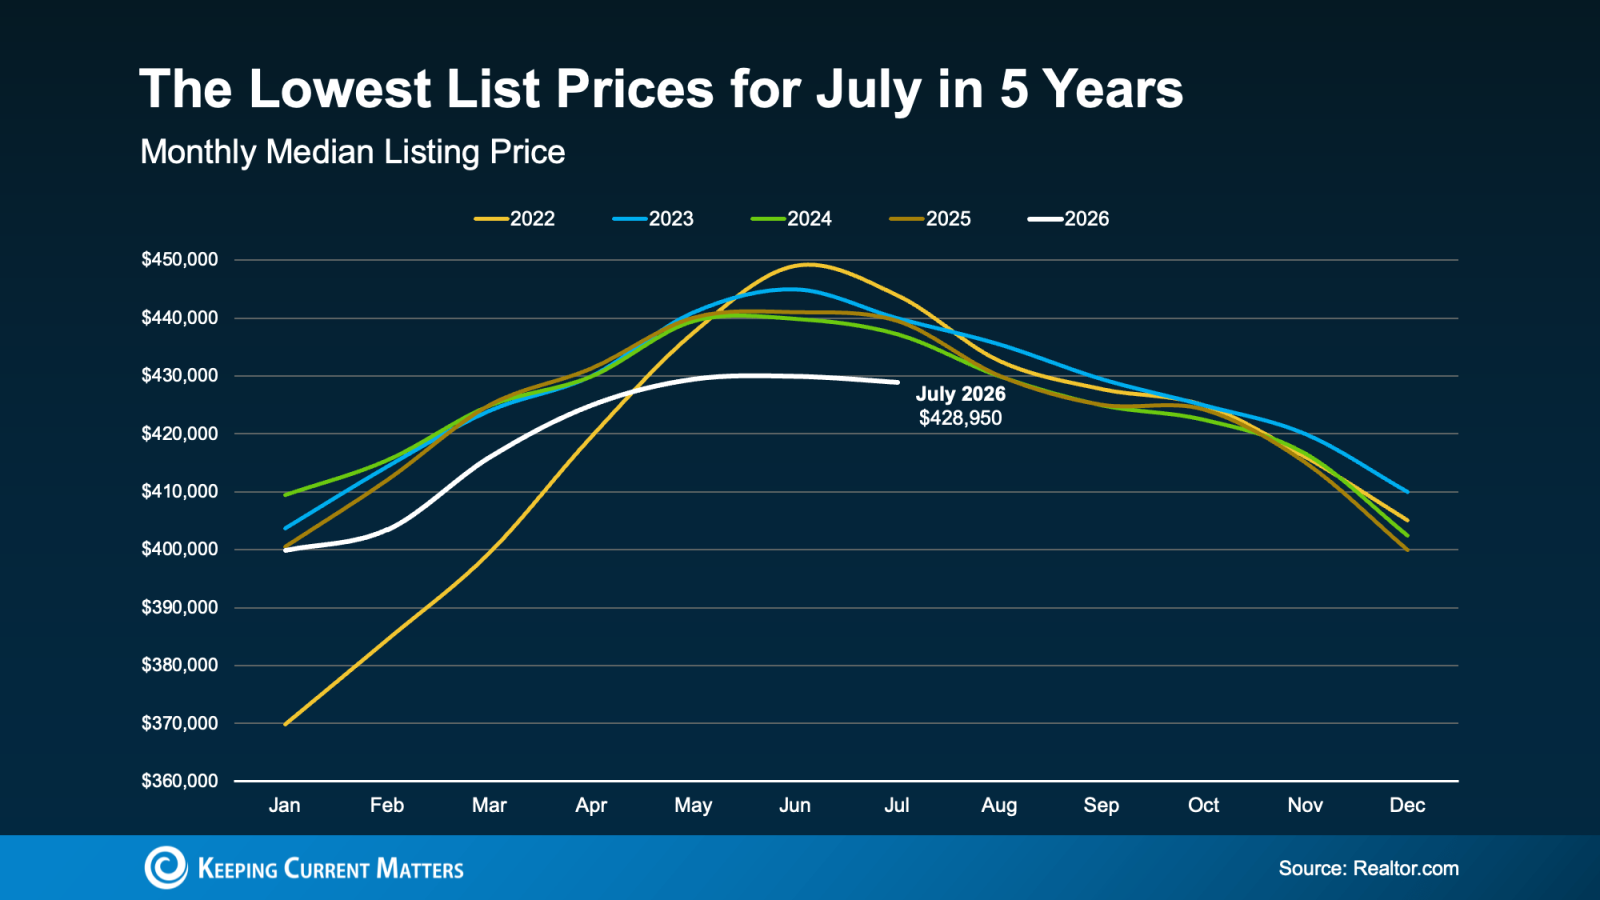
That doesn’t mean homes are suddenly cheap. Home prices are still higher than before the pandemic, and affordability remains a challenge.

But sellers are becoming more realistic about what buyers can afford.

That could mean more opportunities to negotiate—not just on the price, but potentially on repairs, closing costs, and other terms.

What This Means for Buyers

You may not be able to afford every home you see, but don’t assume everything is out of reach.

Today’s market may give you more room to negotiate than you think.

Before ruling out a home based on the asking price, talk with a local real estate agent. They can help you identify price reductions, compare similar homes, and find opportunities where sellers may be willing to work with you.

Sellers are becoming more flexible, and that could create new opportunities for buyers.

If you’re thinking about buying a home, now may be a good time to see what’s actually negotiable in your local market.

Should You Wait for Mortgage Rates to Drop?

If you’re waiting for mortgage rates to fall before buying a home, you may be waiting longer than you think.

For many buyers, mortgage rates have become the biggest reason to stay on the sidelines. The hope is that waiting a few more months will bring significantly lower rates and make homeownership more affordable.

But what if that big drop doesn’t happen?

Current forecasts suggest mortgage rates could remain in the low-to-mid 6% range through at least mid-2027, rather than falling dramatically in the near future.

A recent survey found that 42% of people expect mortgage rates to fall below 5% this year. However, forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo point toward rates remaining relatively steady.


Inflation is one reason. Mortgage rates are influenced by inflation, economic conditions, Treasury yields, Federal Reserve policy, and other factors. With inflation still putting pressure on the economy, a significant decline in mortgage rates may not happen as quickly as many buyers hope.

There’s also an important matter of perspective. Mortgage rates in the 6% range may feel high compared with the historically low rates available during the pandemic, but they are not unusual from a historical standpoint. Mortgage rates have spent much of their time between 5% and 10%.

That means waiting for another return to 3% or 4% rates may not be the most realistic strategy. Instead, buyers may want to focus on finding ways to make the current market work for them.

For example, new construction homes may come with incentives such as rate buydowns, closing-cost assistance, price reductions, or upgrades. Buyers can also ask lenders about adjustable-rate mortgages (ARMs), which may offer a lower initial rate for those who don't plan to stay in the home long-term.

Another option is a mortgage rate buydown, which can potentially lower the interest rate and monthly payment. In some cases, buyers may also find opportunities with assumable mortgages, allowing a qualified buyer to take over a seller’s existing loan and its potentially lower interest rate.

None of this means you need to rush into buying a home. Your financial situation, goals, and timeline should always come first. But if you’re ready to move, waiting indefinitely for lower rates may not necessarily put you in a better position.

Mortgage rates are only one part of the equation. Home prices, inventory, seller incentives, loan programs, and your personal finances all play a role in determining affordability.

Before putting your home search on hold, talk with a trusted real estate professional and lender. They can help you compare different scenarios and determine whether waiting—or making a move in today’s market—makes the most sense for you.

The perfect mortgage rate may be impossible to predict, but the right strategy can make today’s market much easier to navigate.

Displaying blog entries 1-2 of 2

Share This Page

Contact Information

Cindy Wood
Cindy Wood Realty Group
6040 S Fashion Blvd #201
Murray UT 84107
(801) 278-0999
801-891-4559